Oct 15 2026
What's your personal inflation rate?
Those on low or fixed incomes – such as in retirement – may find themselves wondering why their income doesn’t stretch as far as it used to. And it’s not because they’ve been careless with their budgeting. We often talk about the inflation rate as if we all experience the same price increases. But in reality, everybody’s inflation rate is different, because it’s linked to what you buy.
We know people on low incomes have different spending patterns than those on high incomes, and that affects how inflation impacts them.
How it affects retirement
The cost of living for retirees is rising faster than for other New Zealanders. Most people are familiar with the Consumer Price Index (CPI). However, Stats NZ also calculates a Household Living Costs Price Index (HLPI) for different segments of our population, including beneficiaries, Māori, superannuitants, people in different income brackets and people in different spending brackets.
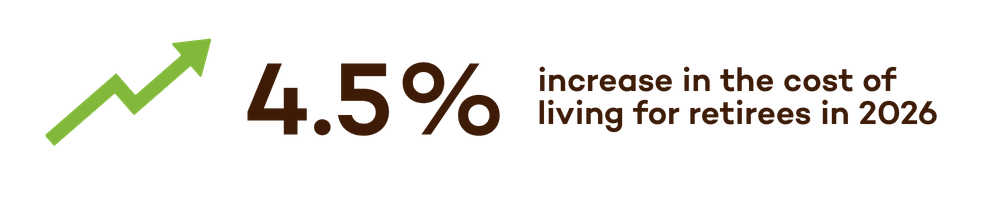
The cost of living for the average New Zealand household, as measured by the HLPI, rose by 3.2% in the year to June 2026. But for those on a pension, costs rose 4.5%. In comparison, people with high spending (and presumably high incomes to match) saw a cost increase of only 1.9%.
The reason for the differences lies in what these groups spend their money on. Let’s look at some of the differences.
Retirees versus a young family starting out
A young couple with a family and a mortgage spend a large chunk of their income on things like childcare, commuting costs and mortgage interest. Interest rates have fallen recently, which has benefited their living costs.
Retirees, on the other hand, spend most of their income on utility costs such as rates, power and phone, and on essentials such as food, petrol, healthcare and insurance. These expenses are difficult to cut back on as they’re the necessities of life. Electricity prices increased by about 8% in the last year, and that’s on top of an 8% increase the previous year. Petrol prices, meanwhile, have gone up by 15%, the average local authority rates bill is up about 9%, and insurance costs have soared. All households spend money on these things, but because retiree incomes are so low, they make up a bigger proportion of total household living costs.
This is important to be aware of as you prepare for retirement. How you experience inflation today may differ from how it affects you in retirement.
The impact on purchasing power
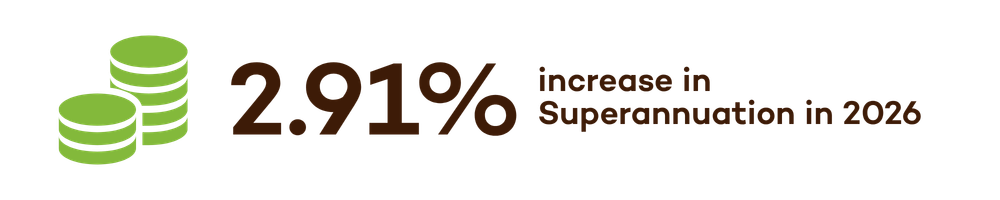
Despite the 4.5% increase in living costs pensioners saw, NZ Super increased by only 2.91% on 1 April 2026. That’s because it’s linked to the increase in net average wages, not living costs. If living costs for retirees increased by 2% more than their income for ten years, their pension purchasing power would fall by nearly 20%. That’s a substantial drop which many retirees would not be able to sustain.
Cutting back on spending is not a practical solution to the inflation problem for retirees. Retirement budgets usually leave little room to move, as most spending goes to essentials. Besides which, retirement is supposed to be enjoyed and being overly frugal is counter to that. Inflation doesn’t mean you should have to stop travelling, going out for dinner or doing all the other things you might enjoy in retirement.
But knowing your own inflation rate in retirement can help you identify pressure points in your living costs so you know where to focus your attention. While many costs are out of a retiree’s control, they can shop around for better deals on things like power, internet and phone costs, and insurance.
Investing for income: the best defence can be offence
Sometimes people react to higher living costs by becoming more defensive and protective with their retirement savings and invest conservatively as a result. In fact, the best defence against inflation is to have at least some of your investments in growth assets such as shares, as this can provide a higher return to help offset your cost increases.
This is particularly important for people starting out in retirement, as their retirement savings may well have to last thirty years. While it’s always important to have spending money on hand in safe investments, such as bank deposits, it’s also important to think about the long term and the effects of inflation on spending power.
The key message here is that the Consumer Price Index doesn’t measure your personal inflation rate. Understanding where your own costs are increasing, controlling the expenses you can and ensuring some of your investments have the potential to grow in value will make a big difference to how long your money lasts in retirement.
Understanding this before you start your retirement can help your money last longer.
Investing for income with Lifetime
The Lifetime Retirement Income Fund uses both growth and more defensive assets to provide regular payments for 20 to 30 years.
Learn more about how we invest for income here: Investing for Income
The advice given here is general and does not constitute specific advice to any person.
Written by: Liz Koh
Liz Koh is a money expert who specialises in retirement planning.